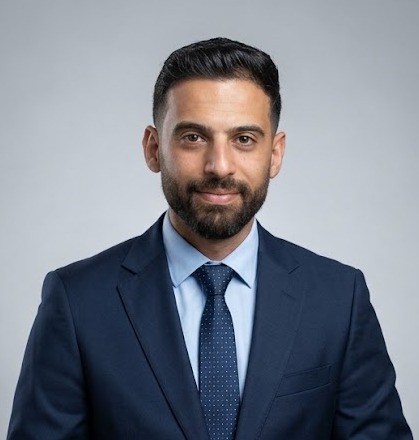
CAIRO — Dr. Baher Abdel Aziz, a finance and investment expert, emphasized the importance of strengthening responsible-finance practices in the microfinance sector as rising prices and household expenses place increasing pressure on borrowers’ repayment capacity.
Abdel Aziz said that a fixed loan installment does not necessarily translate into stable repayment capacity, as higher costs of goods, raw materials, transportation, food, housing, and essential services can significantly reduce the cash available to borrowers.
He stressed that financial institutions should look beyond a client’s current ability to repay and assess how that capacity could withstand potential economic shocks throughout the financing period.
Inflation Can Distort the Picture
According to Abdel Aziz, higher nominal sales resulting from inflation should not automatically be interpreted as an improvement in a microbusiness’s financial position.
A business may record higher revenues in monetary terms while experiencing lower sales volumes, narrower profit margins, and increased working-capital requirements.
“The key measure is not simply the level of sales, but the cash that remains after operating costs, essential household expenses, and existing financial obligations are covered,” Abdel Aziz explained.
He noted that businesses also differ in their ability to pass higher costs on to customers. While some businesses can adjust prices, others serve price-sensitive, lower-income customers, making them more vulnerable to declining demand and shrinking margins.
Responsible Finance Starts with Repayment Capacity
Abdel Aziz emphasized that responsible finance requires lenders to match the financing amount, product structure, and repayment schedule with the client’s actual needs and realistic repayment capacity.
He also highlighted the importance of assessing a borrower’s overall financial obligations, including other outstanding financing where information is available, while taking essential household expenses into account.
A previous record of timely repayment, he noted, remains an important indicator but should not be considered in isolation. Financial institutions should also examine the source of repayment and determine whether installments are being covered by sustainable business cash flows or by new borrowing or the sale of productive assets.
Stress Tests Can Identify Vulnerabilities Before Default
Abdel Aziz said stress testing provides financial institutions with a practical framework to assess how borrowers would perform under more challenging conditions, including higher input costs, declining sales, increased household expenses, or delayed customer collections.
He illustrated the concept with a hypothetical example: if a borrower has EGP 4,000 in monthly cash available after business and household expenses, compared with a monthly installment of EGP 3,000, the borrower has an EGP 1,000 safety margin.
If a stress scenario reduces available cash to EGP 2,500, the borrower would face an EGP 500 shortfall against the installment.
Abdel Aziz clarified that the example is not a standard lending threshold, but rather demonstrates how stress testing can reveal vulnerabilities that may not be visible under normal operating conditions.
He added that the severity of stress scenarios and risk-acceptance thresholds should be determined according to the nature of the business, the institution’s data, and its actual portfolio experience.
Turning Stress-Test Results into Lending Decisions
The value of stress testing, Abdel Aziz said, depends on whether its results are incorporated into financing decisions.
Where testing reveals limited repayment resilience, lenders may consider adjusting the financing amount, repayment schedule, or product structure, or request additional information to better understand the borrower’s business.
For seasonal businesses, for example, repayment schedules may need to reflect the timing of cash flows. In other cases, a lower financing amount may help preserve an adequate liquidity buffer.
Abdel Aziz also cautioned against automatically increasing financing upon renewal or using new financing to cover recurring shortfalls without understanding the underlying causes and assessing the business’s ability to recover.
Portfolio-Level Stress Testing and Early Warning Indicators
Beyond individual borrowers, Abdel Aziz said financial institutions can apply stress tests to groups of similar clients based on business activity, geographic location, or income seasonality.
Such analysis can help institutions identify sectors that are particularly sensitive to inflation and assess potential impacts on repayment delays, liquidity requirements, cash flows, and provisioning.
He also highlighted the importance of early-warning indicators, including declining inventory, slowing sales, repeated requests for payment deferrals, delays in initial installments, and increased reliance on borrowing to meet existing obligations.
“These indicators should trigger an objective review of the client’s position rather than an automatic judgment about their ability or willingness to repay,” Abdel Aziz said.
Governance Supports Sustainable Microfinance Growth
Abdel Aziz stressed that boards of directors and executive management have an important role in embedding responsible-finance principles within lending strategies, monitoring stress-test results, and ensuring that portfolio growth remains aligned with asset quality and product suitability.
He also called for incentive structures that balance loan growth with assessment quality, portfolio performance, and fair treatment of customers, supported by effective internal audit and oversight mechanisms.
“Microfinance institutions need financing models that allow businesses to withstand economic pressures while preserving households’ ability to meet their essential needs,” Abdel Aziz concluded.
He added that early assessment of borrowers’ resilience to economic shocks can contribute to the sustainability of small businesses, strengthen portfolio quality, and reduce default risks.
Sustainable microfinance growth, he emphasized, should be driven by responsible lending and sound credit assessment as much as by portfolio expansion.