Qalaa Holdings consolidated revenue grew 52% y-o-y to EGP 94.7 billion in 1H26 and EBITDA expanded by 403% y-o-y to EGP 30.3 billion, with the Group recording a net profit after minority of EGP 0.2 billion against a net loss after minority of EGP 1.3 billion in 1H25. In June 2026, ERC fully repaid its senior debt, clearing the path for ERC to begin distributing dividends. ERC subsequently paid c.USD 244.0 million of its subordinated debt in August 2026 and another payment of c.USD 118 million is expected shortly. It is worth noting that, ERC has fully repaid the shareholder loan owed to Qatar Energy amounting to USD 104 million, as of 3Q26. Consequently, the Group’s liquidity position has improved materially. Further improvements are anticipated across all major businesses. In September 2026, Qalaa Holdings’ Board of Directors approved the purchase of an additional stake in the Egyptian Refining Company (ERC), raising the Group’s effective indirect ownership from 13.0% to 27.1%. This purchase is expected to close in December 2026. The Board also approved a cash capital increase at nominal value for existing shareholders, raising paid-up capital from EGP 21.1 billion to EGP 25.0 billion.
Key Highlights:
• On a half-year basis, consolidated revenue grew 52% y-o-y to EGP 94.7 billion in 1H26 and EBITDA expanded by 403% y-o-y to EGP 30.3 billion, with the Group recording a net profit after minority of EGP 0.2 billion against a net loss after minority of EGP 1.3 billion in 1H25.
• Qalaa’s consolidated revenue surged by 118% y-o-y to EGP 54.5 billion in 2Q26, driven almost entirely by ERC’s top-line expansion on the back of a rise in petroleum product prices and zero downtime during the quarter, against a pre-planned 32-day maintenance shutdown in 2Q25. Excluding ERC, consolidated revenue was broadly stable, up 2% y-o-y to EGP 5.2 billion. In parallel, EBITDA rose almost ten-fold y-o-y to EGP 18.2 billion. Finally, the Group recorded a consolidated net profit of EGP 2.0 billion in 2Q26, compared to a net loss of EGP 1.2 billion in 2Q25.
• ERC delivered a strong quarter, with refining margins averaging USD 4.3 million per day in 2Q26, up from USD 1.2 million per day in 2Q25, supported by regional market dynamics and higher product prices. The refinery operated all 91 days of the quarter with zero downtime, and the product mix shifted toward lighter, higher-value products. ERC’s revenue rose 147% to EGP 49.4 billion in 2Q26 from EGP 20.0 billion in 2Q25, EBITDA surged to EGP 17.3 billion from EGP 0.8 billion, and the company recorded a net profit of EGP 12.3 billion versus a net loss of EGP 3.8 billion.
In June 2026, ERC fully repaid its senior debt, clearing the path for the company to begin distributing dividends. ERC subsequently paid c.USD 244.0 million of its subordinated debt in August 2026, with the remaining c.USD 559.5 million scheduled for repayment in installments extending through 2030, of which another payment of c.USD 118.0 million is expected shortly. It is worth noting that, ERC has fully repaid the shareholder loan owed to Qatar Energy amounting to USD 104 million, as of Q3 2026.
• Qalaa’s remaining portfolio companies delivered a solid quarter, with every business recording top-line growth with the exception of cement, led by strong momentum across mining, agrifoods, transportation and logistics.
o ASEC Holdings saw solid revenue growth at ASEC Automation and a more than doubling of revenue at ARESCO on the back of new project wins in Egypt and abroad, both of which supported the segment’s top line. The segment’s consolidated revenue nonetheless declined, driven by a drop at ASEC Cement, which was strongly impacted by the devaluation of the Sudanese pound.
o Dina Farms Holding continued to deliver solid top-line growth, driven by improved operations at Dina Farms alongside increased sales volumes, higher selling prices, and the continued scaling of newer product lines at ICDP, most notably ice cream.
o ASCOM recorded strong revenue growth, largely driven by its two largest USD-denominated revenue generators, ACCM and GlassRock, supported by higher sales volumes and improved average selling prices at ACCM and stronger pricing across both product lines at GlassRock. Egypt quarrying revenue also witnessed growth during the quarter. The Group’s position as an import substitute and export player across the mining business continued to strengthen Qalaa’s consolidated top line.
o CCTO’s transportation and logistics business delivered solid top-line growth during the quarter on the back of higher storage volumes and stronger utilization of the inland container depot at NPM.
o TAQA Arabia delivered impressive top-line growth, driven by solid performances across the board.
• The Group continues to focus on growing its exports and leveraging the cost advantage available to local manufacturers, with Group export proceeds reaching c.USD 26.3 million in 2Q26, up 37% y-o-y from c.USD 19.1 million in 2Q25, while local foreign currency revenue surged 137% to c.USD 995.5 million from c.USD 420.2 million over the same period. On a half-year basis, Group export proceeds recorded c.USD 49.0 million, and local foreign currency revenue rose 58% to c.USD 1,730.8 million from c.USD 1,093.7 million in 1H25.
• In 2Q26, Qalaa recorded an interest provision of EGP 503.8 million relating to the debt settlement/restructuring agreements with local banks. This liability continues to be reflected on Qalaa’s balance sheet pending the full satisfaction of all conditions stipulated in the settlement agreement. However, this does not reflect the actual amounts currently owed to these lenders; rather, it represents the pre-settlement balances.
o Qalaa continues to record an interest provision relating to the portion of the Senior Debt that was owed to Egyptian banks, of which EGP 240.8 million was booked in 2Q26. This liability continues to be reflected on Qalaa’s balance sheet pending the full satisfaction of all conditions stipulated in the settlement agreement starting 2030.
o In addition, under the restructuring agreement signed in 2024 between SPVs fully owned by Qalaa and a local bank, a total of USD 44 million, together with all related accrued interest pertaining to loans owed to this bank, which stood at EGP 263.0 million as of 30 June 2026, is expected to be written off following the full repayment of the amounts due to the bank in 2033.
• Qalaa’s strategy will continue to focus on the following elements:
o Qalaa will continue driving growth through small incremental investments in its subsidiaries, expanding cashflows, and thereby reducing its debt to cashflow ratios. Management is confident this strategy will continue to deliver the desired results.
o Strategic plans are underway to initiate five IPOs over the coming two years for select high-growth subsidiaries to unlock shareholder value, enhance financial flexibility, and facilitate the valuation of Qalaa’s shares. National Ports Management (“NPM”) repositioned in 2025 under a new corporate identity from National River Ports Management Company will be among the first subsidiaries offered.
• With ERC’s senior debt now fully repaid and the company able to distribute dividends, the Group’s liquidity position has improved materially. While cashflow bottlenecks persist across some operations, further improvements are anticipated across all major businesses.
• In September 2026, Qalaa Holdings’ Board of Directors approved the purchase of an additional stake in the Egyptian Refining Company (ERC), raising Qalaa’s actual indirect stake in the company from 13.0% to 27.1%. Qalaa will hold a 55.4% shareholding in New Age Refining Ltd, which will purchase the entire share capital of QPI Egypt Ltd, holder of a 25.4% effective indirect stake in ERC, from Qatar Energy at par value. Financial closing is expected in December 2026, subject to the fulfillment of all agreed terms and conditions. The transaction increases Qalaa’s exposure to its largest asset at a point when ERC has fully repaid its senior debt and is positioned to begin distributing dividends.
• The Board also approved a cash capital increase at nominal value for existing shareholders, raising paid-up capital from EGP 21.1 billion to EGP 25.0 billion, with proceeds contributing to funding the purchase of the additional indirect stake in ERC, paying the company’s financial obligations to the Arab International Bank and several Egyptian banks and other creditors, and activating an initial part of Qalaa Holdings’ right to repurchase shares of TAQA Arabia, by buying around 5% of the total shares of TAQA Arabia, targeted for completion before mid-December 2026.
Cairo, 24 September 2026: Qalaa Holdings, a leader in energy and infrastructure (CCAP.CA on the Egyptian Exchange), released today its consolidated financial results for the three-month and six-month periods ending 30 June 2026. Qalaa delivered an exceptional second quarter, with revenue expanding by 118% y-o-y to EGP 54.5 billion in 2Q26, largely as a consequence of the surge in prices of petroleum products, in addition to 2Q25 including the 32-day pre-planned shutdown that impacted ERC’s production. Profitability advanced at an even faster pace, with Qalaa’s EBITDA growing almost ten-fold to EGP 18.2 billion in 2Q26, an 880% y-o-y increase, as the swing to profitability at ERC was backed by improvement in global refining margins driving the Group’s performance. On that front, ERC’s average daily refining margin reached USD 4.3 million per day during the quarter, up 271% from USD 1.2 million per day in 2Q25, with the refinery operating with zero downtime. Consequently, Qalaa reported a consolidated net profit after minority of EGP 2.0 billion in 2Q26, reversing a net loss after minority of EGP 1.2 billion recorded in 2Q25. This was achieved despite the continued accrual of interest expense relating to the Settlement and Restructuring agreements signed in 2024, which amounted to EGP 503.8 million in 2Q26. It is worth noting that this provision is taken on a quarterly basis until the completion of all conditions of the agreement, which is expected to take place starting 2030, at which time the accumulated provision, currently totaling EGP 9.116 billion, will be reversed into a one-time gain. The Group’s momentum was evident over the six-month period, with revenue rising by 52% y-o-y to EGP 94.7 billion in 1H26 and EBITDA growing five-fold to EGP 30.3 billion, a 403% y-o-y increase. In parallel, Qalaa recorded a consolidated net profit after minority of EGP 0.2 billion in 1H26, compared to a net loss after minority of EGP 1.3 billion in 1H25, while ERC’s average daily refining margin stood at USD 3.7 million per day over the period, a 198% increase from USD 1.3 million per day in 1H25.
Qalaa’s consolidated revenue surged by 118% y-o-y to EGP 54.5 billion in 2Q26, compared to EGP 25.1 billion in 2Q25, largely due to the sharp growth in ERC’s revenue during the quarter.
ERC’s revenue rose by 147% y-o-y in EGP terms to EGP 49.4 billion, driven by the strong rise in petroleum product prices, alongside zero downtime during the quarter against a 32-day pre-planned maintenance production shutdown in 2Q25.
Excluding ERC, Qalaa’s revenue was broadly stable, edging up 2% y-o-y to EGP 5.2 billion in 2Q26, as strong growth at ASCOM, Dina Farms Holding, and CCTO offset a decline at ASEC Holdings.
In 2Q26, Qalaa’s recurring EBITDA rose almost ten-fold y-o-y to EGP 18.2 billion, largely as a result of the expansion in EBITDA reported at ERC.
ERC’s 2Q26 EBITDA surged to EGP 17.3 billion from EGP 0.8 billion in 2Q25, on the back of the improvement in refining margins, which averaged USD 4.3 million per day during the quarter against USD 1.2 million per day in 2Q25, as well as the absence of maintenance downtime.
Excluding ERC, Qalaa’s 2Q26 EBITDA declined by 13% y-o-y to EGP 919.4 million, weighed down by margin compression at the Cement platform.
In 2Q26, ASEC Holdings’ EBITDA contracted by 35% y-o-y to EGP 353.7 million, largely reflecting a weaker quarter at ASEC Cement Group, due to the depreciation of the Sudanese pound during the quarter. This was partly cushioned by ASEC Automation, where EBITDA expanded by 45% y-o-y on a greater contribution from international business and higher-margin segments, and by ARESCO, where EBITDA rose 40% y-o-y.
EBITDA at Dina Farms Holding Company was broadly flat, declining 1% y-o-y to EGP 315.8 million in 2Q26, as a 47% y-o-y expansion at ICDP, supported by higher selling prices and volume growth concentrated in higher-margin categories, which was offset by cost pressures at Dina Farms, related to the herd expansion, noting that the resulting increase in milk production is expected to kick-in during future quarters.
ASCOM’s EBITDA grew by 35% y-o-y to EGP 204.5 million in 2Q26, driven by an increase in sales volumes and a rise in average selling prices at ACCM, alongside a 150% y-o-y EBITDA expansion at GlassRock on higher prices across both product lines.
EBITDA at CCTO’s transportation and logistics business rose by 15% y-o-y to EGP 91.9 million in 2Q26, mainly on the back of higher storage volumes and an 83% y-o-y increase in twenty-foot equivalent units handled at NPM’s inland container depot.
Finally, TAQA Arabia’s EBITDA expanded by 35% y-o-y to EGP 818.4 million in 2Q26, supported by broad-based growth across the board. TAQA Arabia is accounted for as an investment in associate using the equity method and revenues are not included in Qalaa’s consolidated revenues.
Qalaa reported a consolidated net profit after minority interest of EGP 2.0 billion in 2Q26, compared to a net loss of EGP 1.2 billion reported in 2Q25. The Group’s bottom-line turnaround came largely on the back of the net profit reported at ERC, notwithstanding the continued accrual of interest expense relating to the Settlement and Restructuring agreements signed in 2024, which amounted to EGP 503.8 million in 2Q26. Interest continues to accrue on Qalaa’s Income Statement pending the full satisfaction of all conditions stipulated in the settlement agreement. However, these amounts will be completely written off once the terms of the settlement agreement are fully met.
In parallel, bank interest expense fell by 22% y-o-y to EGP 1.3 billion in 2Q26, reflecting ERC’s continued deleveraging.
Profitability was broad-based across Qalaa’s platforms during the quarter, led by ERC.
In 2Q26, ERC reported a net profit of EGP 12.3 billion, compared to a net loss of EGP 3.8 billion in 2Q25, largely as a result of the recovery in refining margins during the quarter, as well as the absence of maintenance downtime.
ASEC Holdings achieved a net profit of EGP 109.6 million in 2Q26, a 61% y-o-y decline from EGP 284.4 million in 2Q25, as a large foreign exchange loss at Al-Takamol Cement on SDG depreciation weighed on the platform’s bottom line. This was partly offset by Zahana Cement’s return to profitability, with a net profit of DZD 200.2 million against a net loss of DZD 84.9 million in 2Q25.
At Dina Farms Holding Company, net profit stood at EGP 107.6 million in 2Q26, a 38% y-o-y increase driven by the rise in net income at ICDP.
ASCOM swung to a net profit of EGP 73.3 million in 2Q26, compared to a net loss of EGP 56.6 million recorded in 2Q25, pointing to improved cost efficiency and operating leverage during the quarter.
In 2Q26, CCTO’s transportation and logistics business narrowed its net loss to EGP 4.3 million, from a net loss of EGP 21.5 million in 2Q25, as NPM’s net income grew 55% y-o-y to EGP 64.2 million on lower financing cost and higher operating profit.
Finally, TAQA Arabia’s net profit rose by 65% y-o-y to EGP 353.4 million in 2Q26, fueled by strong bottom-line growth across its subsidiaries.
In June 2026, ERC fully repaid its senior debt. Full repayment opens the door for ERC to distribute dividends. The company subsequently paid c.USD 244.0 million of its subordinated debt in August 2026, with the remaining c.USD 559.5 million to be repaid in installments extending through 2030, of which another payment of c.USD 118.0 million is expected shortly.
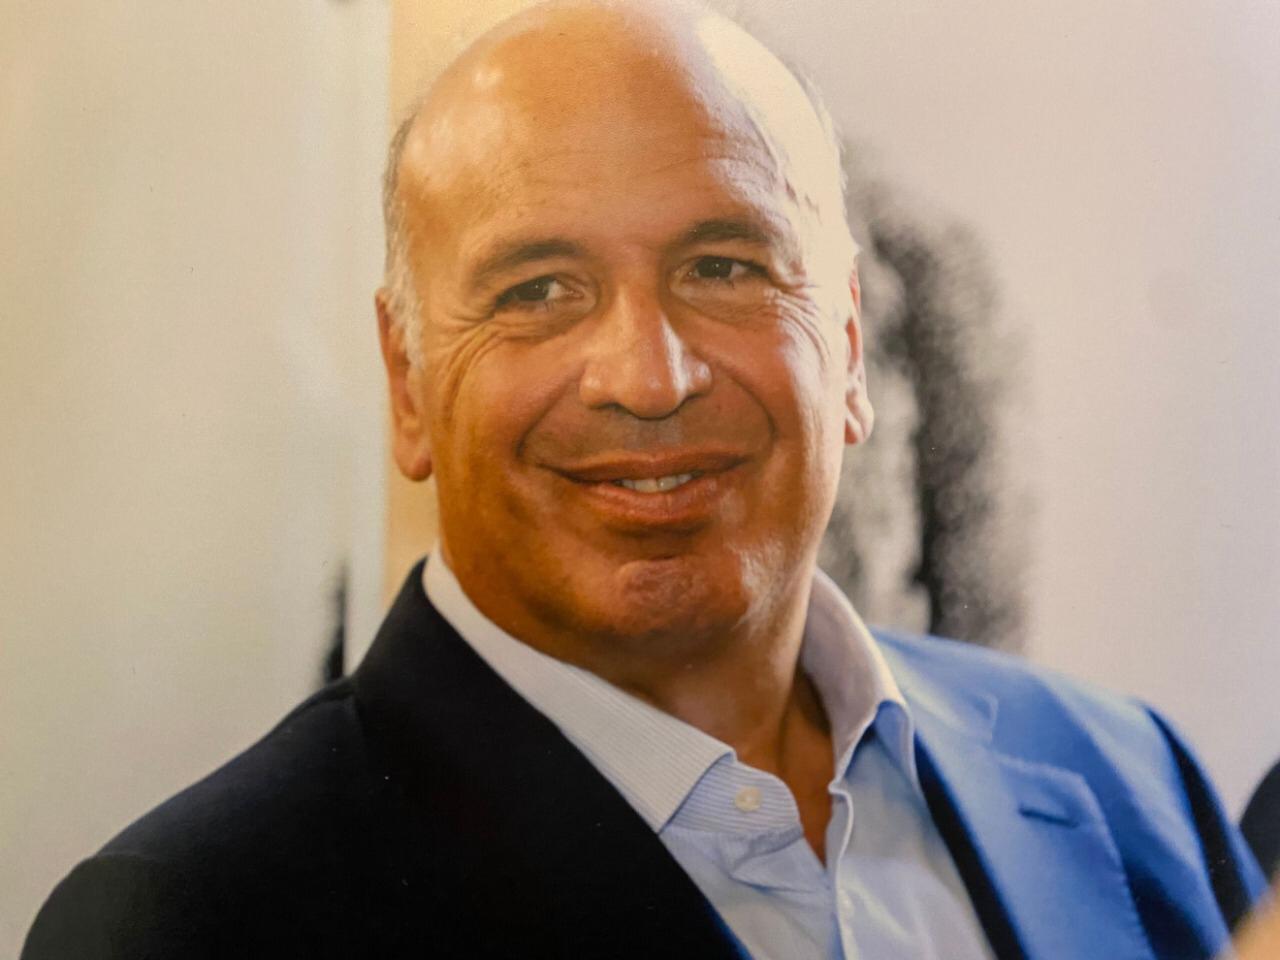
“The first half of 2026 was a strong period for Qalaa across the board, with the Group delivering robust top-line growth, a marked expansion in operating profitability, and a return to net profit,” said Qalaa Holdings Chairman and Founder Ahmed Heikal. “Consolidated revenue expanded by 118% y-o-y to EGP 54.5 billion during the second quarter, while EBITDA surged almost tenfold y-o-y to EGP 18.2 billion, driving the Group to a net profit after minority interest of EGP 2.0 billion in 2Q26 against a net loss of EGP 1.2 billion in 2Q25. This performance was led by an exceptional quarter at the Egyptian Refining Company, which operated with no shutdown time, against a 32-day pre-planned maintenance shutdown in 2Q25 and benefitted from a sharp expansion in refining margins to an average of USD 4.3 million per day, up from USD 1.2 million per day in the corresponding quarter.”
“Adding to the milestones achieved, in September 2026, our Board approved a transaction that more than doubles Qalaa’s effective indirect stake in the Egyptian Refining Company from 13.0% to 27.1%, through its 55.4% shareholding in New Age Refining Ltd, which will buy all the shares of QPI Egypt Ltd, which is fully owned by Qatar Energy. This is precisely the kind of value-accretive opportunity we have been working towards: it deepens our exposure to our largest and best-performing asset at a moment when ERC has fully repaid its senior debt and is positioned to distribute dividends.
Alongside it, the Board approved a cash capital increase raising paid-up capital from EGP 21.1 billion to EGP 25.0 billion, the proceeds of which will help fund ERC purchase of additional stake, pay Qalaa’s financial obligations to the Arab International Bank and several Egyptian banks and other creditors, and activate an initial tranche of our right to repurchase shares in TAQA Arabia. We are targeting completion of both before mid-December 2026.” Heikal noted.
“Beyond ERC, our operating platforms continued to demonstrate the strength of their fundamentals, with the Group swinging to a net profit of EGP 441.9 million excluding ERC during the quarter, compared to a net loss of EGP 739.0 million in 2Q25. Our mining platform delivered strong double-digit top- and bottom-line turned to profitability, our agrifoods platform sustained solid revenue momentum, and TAQA Arabia posted impressive results across the board. At our cement platform, Al-Takamol Cement sustained its recovery with solid growth in revenue and sales volumes, while Zahana Cement returned to profitability on the back of higher sales volumes. Alongside this, ASEC Automation and ASEC Engineering each delivered double-digit top-line growth during the quarter, while ARESCO achieved triple digit growth.”
“I am particularly pleased with the significant progress achieved on the debt settlement front, as we continue to work towards strengthening and enhancing the Group’s overall financial position. As we head further into the year, we remain focused on executing our growth strategies across our various platforms, while simultaneously keeping a close eye on any emerging value accretive investment opportunities that will strengthen our overall investment portfolio. I remain confident in Qalaa’s ability to navigate and capitalize on a dynamic operating environment by leveraging the resilience and agility ingrained in our DNA, while continuing our deleveraging journey.” Heikal added.
“Finally, I would like to reiterate that the true value of Qalaa’s performing assets is masked due to holding them at their historical cost and, in some cases, adjusting for impairments, while not taking into consideration any revaluation adjustments,” Heikal concluded.
“From an operational standpoint, the quarter highlighted both the earnings power of ERC and the growing contribution of our wider portfolio,” said Hisham El-Khazindar, Qalaa Holdings Co-Founder and Managing Director. “At ERC, revenue rose 147% y-o-y to EGP 49.4 billion in 2Q26 from EGP 20.0 billion in 2Q25, driven mainly by higher petroleum product prices, while the refining margin upcycle that started in 4Q25 continued to gain pace through the first half. Across our other platforms, performance was driven by clear operational improvements. Our mining operations continue to benefit from their dual role as an import substitute and an exporter, giving Qalaa a valuable stream of hard-currency proceeds. In agrifoods, growth came from higher volumes and pricing as well as the scaling of newer product lines at ICDP, while our logistics platform delivered solid revenue and EBITDA growth and significantly narrowed its net loss.”
“On the debt settlement front, ERC fully repaid its senior debt in June 2026, having reduced the principal balance from an initial USD 2.35 billion, a milestone that now opens the door for ERC to distribute dividends. The company subsequently paid c.USD 244.0 million of its subordinated debt in August 2026, with the remaining c.USD 559.5 million to be repaid in installments extending through 2030, of which another payment of c.USD 118.0 million is expected shortly. In parallel, ERC has no outstanding receivables from EGPC, which is presently current on all its payments due to the company,” added El-Khazindar.
“With the performance delivered during the first half of the year, I am positive that Qalaa remains well positioned to deliver consistent and sustainable results over the coming period. With that, I look forward to additional quarters of continued growth, gains, and strong results across our diverse markets and operations,” concluded El-Khazindar.